What are payday loans?
Making financial decisions on the fly is difficult because of failure to predict the ramifications of the choices. Cash to payday loans provide fast upfront cash to those who may not have the time to wait for alternative options or do not qualify for other options. However, these loans come with a steep interest rate and generally, that amount of interest accrues immediately. Cash to payday loans are used for necessary functions, such as paying for a quick auto repair or medical bill, while others use these loans to pay for extravagant items such as clothing, car loan payments, etc. The loan providers choose to locate their services in proximity to demographics that cannot usually afford them. Those being communities where financial literacy education is not provided and where people face harsh economic circumstances.
How do payday lenders find clientele?
Many lenders provide services in-person, mostly in impoverished areas, and on the internet for online goods that are on an interval payment system. “Storefront lenders are the public face of payday lending: Money Mart, Cash Money, and other chains and single stores in Canada and Advance America, ACE Cash Express, and others in the USA”(Robinson & Robinson, 1970). Lenders that provide buy now pay later services, such as Klarna or Afterpay, target a certain age and racial demographic that are vulnerable to debt traps without the proper education. Although these lenders are required to display terms of service and interest rates to their customers, they are not required to highlight these in bright colors. However, these services do make machines similar to ATMs and online user experiences both easy and visually appealing to capture the attention of customers. Purchaser’s of these buy/lend now pay later options are not realizing the negative consequences of their credit, debt, and future financial service ability.
Afterpay and Klarna are relatively new services that allow online customers to purchase an item and pay back in installments. Many of these systems are embedded in ecommerce stores, such as H&M, Walmart, ASOS, and more; companies that are facing other ethical issues for how their fabrics and clothes are sourced and manufactured. However, focusing on the financial ability of their customers to pay, it shall be deemed unethical to provide ways for customers who cannot afford these items to owe the lenders and increase their margins.
The price of paying later
“Klarna says its official ‘default’ rate of paying back stands at 0.4% (referring to the number of people who never pay back). There are 3% of borrowers failing to pay back after 3 months, and an independent report found a further 5% pay “late”. While these numbers may seem pretty low, these figures may underreport and underrepresent the rate of users in financial difficulty. Consumers may have to borrow money from friends and struggle privately, making spending cuts elsewhere to ensure they can pay off their debt” (Emily, 2021). Generally, these merchants target young, at-risk, uneducated buyers into purchasing lavish items they cannot afford. Examples of purchases one could make with Klarna included expensive clothing, electronics and other non-essential goods.
There are general high interest rates and fees associated with payday loaning. One issue is that these loans often target vulnerable populations, such as low-income individuals or those with poor credit scores. These individuals may not have access to traditional forms of credit, making them more likely to turn to payday loans as a last resort. This can lead to financial hardship and even bankruptcy. Many borrowers may not fully comprehend the high interest rates and fees associated with the loan, leading them to take out loans that they cannot afford to repay. In addition, the loan providers may use aggressive tactics, such as automatic renewals or withdrawals from the borrower's bank account, to ensure repayment of the loan. These practices can further trap borrowers in a cycle of debt, ultimately leading to financial instability and distress. Overall, payday loans raise significant ethical concerns regarding the exploitation of vulnerable individuals and the lack of transparency in lending practices.
Borrowers can end up paying a lot of money over the life of the loan. For example, a $500 loan with a 300% interest rate would cost the borrower $1,500 to repay over the life of the loan. The high interest rates and fees associated with payday loans can put borrowers in a cycle of debt. Many borrowers find themselves unable to repay the loan in full by the due date and end up renewing the loan, incurring additional fees and interest. This cycle can continue for months or even years, resulting in borrowers paying back much more than they originally borrowed. It is unjust to offer these types of loans to individuals who are likely to struggle to repay them and potentially face long-term financial consequences.
How does this happen?
The payday loan industry also has more lax regulations than some of the cornerstone lending institutions, such as credit unions or FDIC insured banks. Payday lenders often operate without transparency, making it difficult for borrowers to fully understand the terms and conditions of their loans. Unlike other types of lenders, payday lenders are not subject to the same regulations, which means that they may not be required to disclose the full cost of the loan or any hidden fees. This lack of transparency can lead to predatory lending practices, where lenders take advantage of vulnerable borrowers who are in desperate need of money. It is imperative that payday lenders and buy now pay later systems be subject to stricter regulations, such as limits on interest rates and fees.
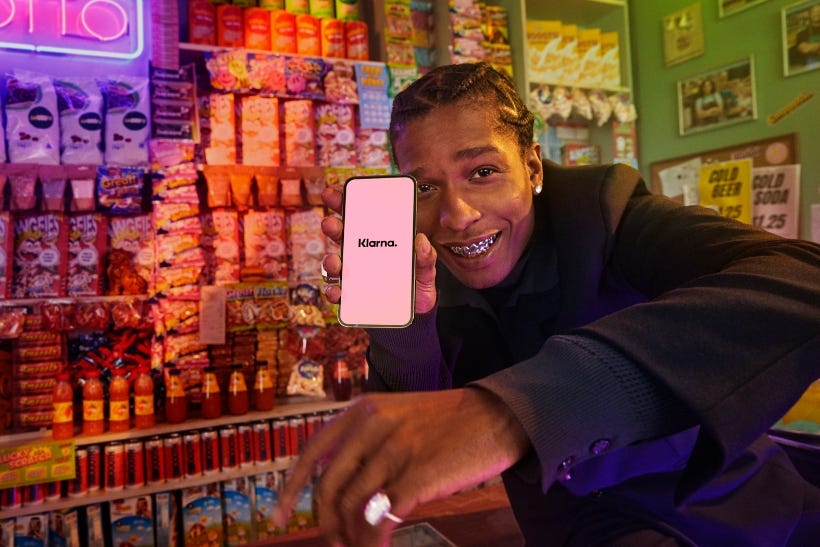
There are marketing moves made to persuade consumers to use these services, which too should be monitored. Klarna used musical artists ASAP Rocky to advertise their 2020 advertising campaign in an attempt to increase e-ecommerce sales of clothing and popular accessories. While unique, it is unethical to put a celebrity on a pedestal to persuade customers to use these financial services. Again, because of the type of lending they provide, they are not required to highlight the pitfalls of not paying the bill in a timely manner and lead many down a path of debt and poor credit. Many celebrities have been grilled for promoting financial services such as crypto, and have received fines for doing so. However, this is not the case in these payday schemes. Instead, these companies get off scot-free because they benefit all transactional parties, minus the customer.
The payment processors are able to charge higher rates, the site or platform increases its revenue, and they accrue a massive amount of interest on these charges. Money Mart, Klarna, and more should face stricter regulation by the regulators. This should require more up-front transparency to customers so that they are not victims to high interest rates, debt cycles, and putting their future lending options at peril. Also, celebrities should not be allowed to highlight financial services in the United States. Because of their status, they make customers feel safe conducting business with these different platforms. If Madoff and FTX face backlash for highlighting celebrities as trusted individuals to influence people to use their platforms, companies similar to Afterpay should face the same scrutiny. Individuals looking for cash should look to credit unions and other banks to protect themselves against these predatory institutions. It may be only a matter of time until these companies face their day in congress or the hammer comes down from regulators in D.C.